A tax change scheduled for October 1 did not arrive as originally planned. British Columbia paused the expansion of provincial sales tax to professional services, including non-residential real estate commissions, trading services, rental-property management and strata-management services.[1][2][3]
That matters most to owners, buyers and investors dealing with commercial or mixed-use property. It does not mean every real-estate cost in B.C. is suddenly tax-free, and it does not create a new discount on ordinary residential home purchases. The original expansion targeted non-residential real estate services; services for property entirely classified as residential or supportive housing were outside that category.[3]
The practical message is simple: do not add the planned 7% PST to a commercial real-estate budget as though it took effect today, but do not delete tax review from the transaction checklist. The pause is being maintained through a temporary regulation, and property classification, invoice timing and the exact service still matter.[1]
The planned tax on non-residential real estate services did not take effect today.
THE CHANGE
What B.C. changed before October 1
Budget 2026 had set out a 7% PST expansion for several professional-service categories beginning October 1. The list included accounting and bookkeeping, architecture, engineering and geoscience, security and private investigation, and non-residential real estate services.[2]
On September 18, the Province announced that the expansion would be paused. Its release says the exemption will be maintained for the affected professional services, specifically naming non-residential real estate commissions and services. The Province described the mechanism as a temporary regulation and estimated approximately $260 million in savings for people, businesses and local governments during 2026-27 across the whole paused professional-services package—not real estate alone.[1]
The distinction between a pause and a repeal matters. A pause says the planned charge is not being applied now. It does not guarantee that the policy can never return, and the provincial release does not provide a new implementation date. Contracts, purchase analyses and operating budgets should therefore state the current treatment and identify tax change as a future sensitivity rather than assuming a permanent exemption.[1]
For a live transaction, use the current invoice and written advice from the brokerage, lawyer, accountant or tax professional. An older estimate prepared before September 18 may still show the planned PST. A current estimate should not quietly carry that superseded assumption forward.
THE SCOPE
Which real-estate services were in the planned tax
The Province’s detailed guidance describes non-residential real estate services as licensed real-estate trading, rental-property management and strata-management services related to non-residential property in B.C. It says real-estate commissions and fees on the sale or lease of non-residential real estate fall within trading services.[3]
The scope was not the purchase price of the commercial building itself. It was the purchase price of the taxable service—such as a brokerage commission or qualifying management service. Rent itself and strata fees were also not classified as non-residential real estate services under the detailed guidance.[3]
This is why a headline saying “7% commercial property tax” would be misleading. The planned expansion was not a new 7% charge on the value of a $2-million building. It was 7% on the taxable professional-service fee. If a qualifying commission were $40,000, the planned PST would have been $2,800. If the fee were $25,000, the planned tax would have been $1,750. Under the announced pause, that additional charge is not currently being applied through this expansion.[1][3]
Other taxes and closing costs remain separate. Property transfer tax, GST where applicable, legal fees, financing costs, adjustments and existing PST rules for other goods or services do not disappear because this one expansion was paused. Every acquisition or disposition still needs a transaction-specific statement of adjustments and professional tax review.
RESIDENTIAL
Residential homes were not the target
The clearest consumer fact is also the easiest to miss: the planned category excluded services for property entirely classified as Class 1 Residential or Class 3 Supportive Housing under the Assessment Act. A typical resale house, residential condominium or residential townhouse was not supposed to acquire this new PST on real-estate services merely because October 1 arrived.[3]
That means a residential seller should not advertise the pause as a new 7% saving on the home price or as a temporary reason to list. A residential buyer should not expect the purchase price, mortgage, property transfer tax or ordinary closing costs to fall by 7%.
Residential real-estate services can still be subject to GST under federal rules, and a transaction can include taxable products or services outside the paused provincial expansion. Rico is not acting as a tax adviser. Buyers and sellers should ask the service provider to identify each tax shown on an estimate rather than relying on a social-media summary.
For most South Okanagan and Similkameen home buyers and sellers, the useful takeaway is therefore narrower: this pause should not change the residential offer price. It is more relevant when the property, service or ownership plan has a commercial component.
MIXED USE
Mixed-use property needs a closer look
Mixed-use real estate is where the original guidance became more technical. The Province said that when a property was classified partly as residential or supportive housing, the portion of the service reasonably attributable to that residential part would not be included in the taxable purchase price. Its example used a property that was 20% commercial and 80% residential; only the commercial portion of the commission would have attracted the planned PST.[3]
The pause means that calculation is not producing the new tax today, but the underlying classification question remains useful. A storefront with apartments above it, a live-work property, a farm with commercial improvements, a mixed-use strata or a building with several assessment classes cannot always be analyzed like a conventional house.
Do not assume that physical square footage, rental income, zoning, listing remarks and BC Assessment classification will always point to the same answer. The provincial guidance allowed reasonable attribution and included special treatment for property that had not yet been classified. The professional preparing the invoice should explain the basis used, and the buyer or seller should keep that written explanation with the transaction records.[3]
This also affects budgeting beyond tax. Commercial and mixed-use financing may use different down-payment, appraisal, environmental, lease-review, insurance and debt-service criteria. A paused service tax can reduce one projected cost without making the property residential or changing the lender’s underwriting.
SPECIAL CASES
Farmland and self-managed property were separate cases
The detailed provincial guidance also listed an exemption for non-residential real estate services related to Class 9 farmland. For a mixed-use property, only the service portion reasonably attributed to the farmland classification or qualifying improvements would have received that exemption under the planned rules.[3]
It also said the non-residential service category did not include a company providing services to its own properties. A landlord’s own internal work and a licensed third-party property-management service are not necessarily treated the same way.[3]
Those distinctions are relevant in the South Okanagan and Similkameen, where a search can include orchards, vineyards, agricultural land, roadside retail, hospitality, workshops, storage, mixed residential-commercial buildings and conventional residential homes. The word “farm,” “acreage” or “investment” in marketing copy is not a tax classification.
Before calculating a return, identify the legal parcel, current assessment classes, permitted and actual uses, leases, service contracts and whether the quoted professional is supplying a taxable service under the current law. A pause in one tax measure does not validate the use, confirm farm status or answer GST and income-tax questions.
AUDIENCE GUIDE
What this means for you
ACTION PLAN
A practical transaction checklist
- Identify the property class. Obtain the current BC Assessment record and do not substitute the listing’s marketing category for the legal or tax classification.
- Separate the costs. List the purchase price, commission, property management, strata management, legal work, appraisal, environmental review, financing, insurance, transfer taxes and GST as separate lines.
- Update old estimates. Ask any professional who prepared a pre-September 18 quote whether it included the now-paused expansion.
- Confirm mixed-use allocation. For a residential-commercial property, request the written basis for allocating fees between portions rather than applying 7% to the whole service by default.[3]
- Stress-test the future. Model the deal with no new PST under the present pause and with a 7% charge on the affected service if the policy later returns. That is scenario planning, not a prediction.
- Read leases and contracts. Check who is responsible for taxes on service fees, how additional charges can be passed through and whether quoted amounts are tax-inclusive.
- Get the right advice. Use a lawyer or notary for legal structure, an accountant or tax professional for tax treatment, a lender or mortgage broker for financing and qualified inspectors or consultants for the property itself.
A cost that is absent today can still belong in the risk section of an investment model. Conversely, adding a hypothetical tax to current cash requirements can make a viable transaction look worse than the law presently supports. Label current costs and contingencies separately.
RICO’S VIEW
Rico’s practical read
The pause is useful real-estate news because it changes a cost assumption for commercial and mixed-use decisions at the exact date the charge was supposed to begin. The “wow” fact is not that B.C. removed 7% from every property purchase. It is that the 7% professional-service tax did not take effect as planned, and its real-estate scope was narrower than many people may assume.[1][2][3]
For a residential client, the correct response is usually no change to the offer strategy. For a commercial investor or mixed-use owner, the correct response is to update the closing or operating model, preserve the classification evidence and keep a future-policy sensitivity in the file.
If you are comparing homes, the Property Matchmaker can narrow the search by location and property needs. Owners considering a sale can begin with the Sell page. For a South Okanagan or Similkameen property conversation, contact Rico.
This article provides general real-estate information, not tax, accounting, legal, investment, lending or appraisal advice. The Province may amend legislation, regulations or administrative guidance. Confirm the current treatment of your exact property, service, invoice and transaction with the appropriate qualified professionals.
Sources
- Province of B.C. — B.C. pauses PST expansion to professional services
- Province of B.C. — Notice 2026-001
- Province of B.C. — PST on non-residential real estate services
- Wikimedia Commons — Penticton former post office / Nanaimo Square shops

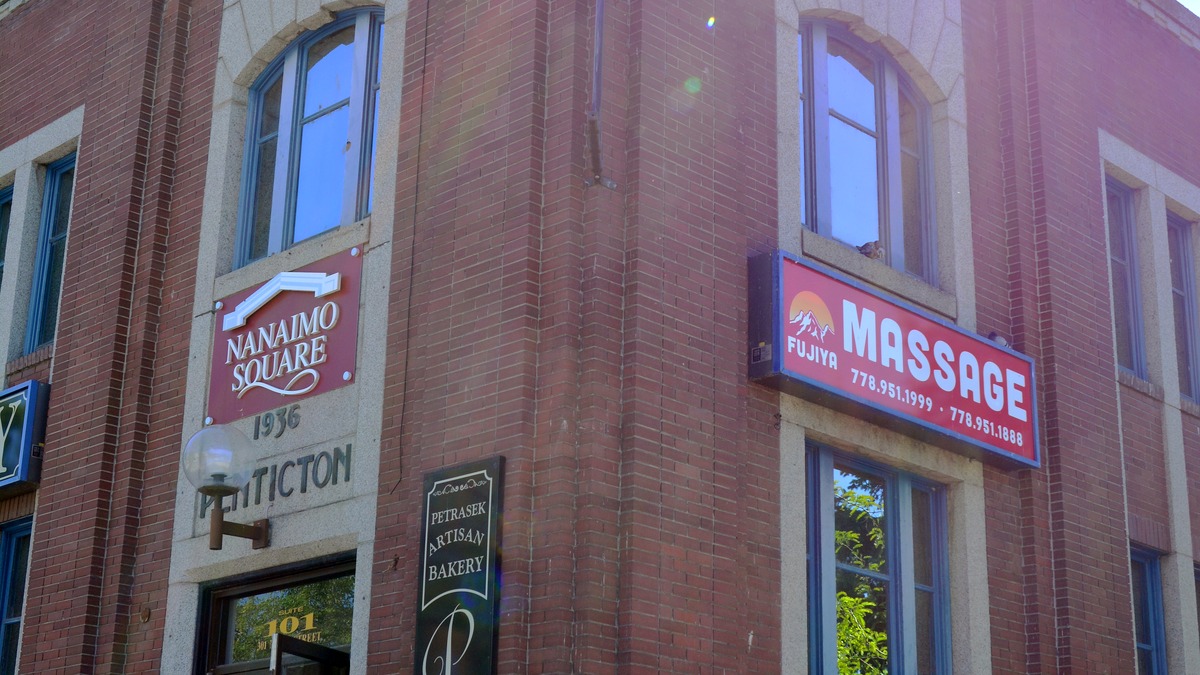
Image credit: Joe Mabel, Wikimedia Commons, CC BY-SA 4.0. Authentic June 6, 2023 photograph of Penticton’s former post office, now Nanaimo Square shops. Representative local commercial-property context only; not a listing, subject transaction or statement about a tenant or owner. Cropped and lightly contrast-adjusted; derivative retained under CC BY-SA 4.0.
Turn the information into your next step
Choose the path that matches the decision you are making now.
Planning a Penticton move? Explore Rico’s Penticton real estate guidance and current listings.